 blog
7 Home Maintenance Mistakes That Trigger Claim Denials
Last Updated: November 18, 2026
Quick Summary
The most common home maintenance mistakes that cause claim denials are ignoring small leaks until they become water damage, skipping seasonal roof and gutter checks, never documenting maintenance, and confusing sudden damage with gradual deterioration. Insurers deny claims when damage looks like neglect or wear and tear rather than a sudden, accidental loss. Delaying claim reporting and overlooking policy exclusions also trigger denials.
- Check under sinks, around the water heater, and behind the washing machine once a month for leaks.
- Clear gutters and check shingles twice a year, in spring and fall.
- Keep a dated photo log, receipts, inspection reports, and a simple yearly maintenance log.
- Report a loss as soon as you find it and keep receipts for emergency repairs.
- Floods, earthquakes, and neglect are typically excluded, and flood coverage needs a separate policy.
Table of Contents
- Why Insurers Tie Claim Denials to Maintenance History
- Mistake 1: Ignoring Small Leaks Until They Become Water Damage
- Mistake 2: Skipping Seasonal Roof and Gutter Checks
- Mistake 3: Never Documenting Home Maintenance
- Mistake 4: Confusing Sudden Damage With Gradual Deterioration
- Mistake 5: Delaying Claim Reporting After a Loss
- Mistake 6: Overlooking Common Homeowners Insurance Claim Denial Reasons
- Mistake 7: Missing the Warning Signs of a Water Damage Insurance Claim Denial
- Frequently Asked Questions
Why Insurers Tie Claim Denials to Maintenance History
Most homeowners assume their policy pays for any damage that isn't their fault. The fine print says otherwise. Insurance policies are contracts built around one idea: the insurer covers sudden, accidental losses, not damage that built up over months or years because nobody checked.
That distinction is where common home maintenance mistakes that cause claim denials start to matter. A small leak or worn roof flashing that goes unaddressed can leave a home exposed, and when a storm finishes the job, the claim may be denied because the damage didn't happen suddenly.
The Insurance Information Institute's guide to homeowners insurance puts it plainly. A standard policy covers named perils like fire, wind, and sudden water damage. It does not cover neglect or wear and tear. Your maintenance history is the evidence an adjuster uses to decide which one applies.
Below, we walk through the seven mistakes that show up most often in denied claims, and how to avoid each one.
Mistake 1: Ignoring Small Leaks Until They Become Water Damage
A slow leak under a sink is easy to ignore. It drips into a cabinet, stains the wood, and feeds mold for months. By the time a pipe bursts, the insurer sees long-term seepage, not a sudden loss.
Water damage is the most common reason home claims get denied, and slow leaks are usually the culprit. Insurers generally distinguish between:
- Sudden water damage - a burst pipe or appliance failure. Often covered.
- Gradual seepage - a leak that ran for weeks. Often excluded as neglect.
The fix is simple. Check under sinks, around the water heater, and behind the washing machine once a month. Look for rust, warping, or a musty smell.
If you're already dealing with a leak and wondering whether your policy responds, our guide on whether homeowners insurance covers water damage from leaks explains which leaks are excluded and how to document a claim so it gets paid.
Mistake 2: Skipping Seasonal Roof and Gutter Checks
Clogged gutters cause more roof claims than most homeowners realize. Water backs up under the shingles, rots the decking, and finds its way into ceilings. An adjuster who sees years of debris and water staining will call it deferred maintenance.
Two checks a year cover most of the risk:
- Spring: clear gutters, check downspouts, look for loose or missing shingles.
- Fall: clear leaves before the first freeze, check flashing around chimneys and vents.
The FEMA guidance on protecting your home from water damage recommends keeping gutters and drainage clear as a first line of defense. It's cheap work that prevents expensive claims.
Not sure what to look for up there? Our checklist of early warning signs of roof failure covers the seven things worth checking before damage spreads.
Mistake 3: Never Documenting Home Maintenance
Here's a mistake that costs homeowners claims they should have won. They did the work, but they can't prove it. No receipts. No photos. No record of the roof inspection two years ago.
Most advice on this topic focuses on photographing damage after it happens. That is necessary, but it is not enough.
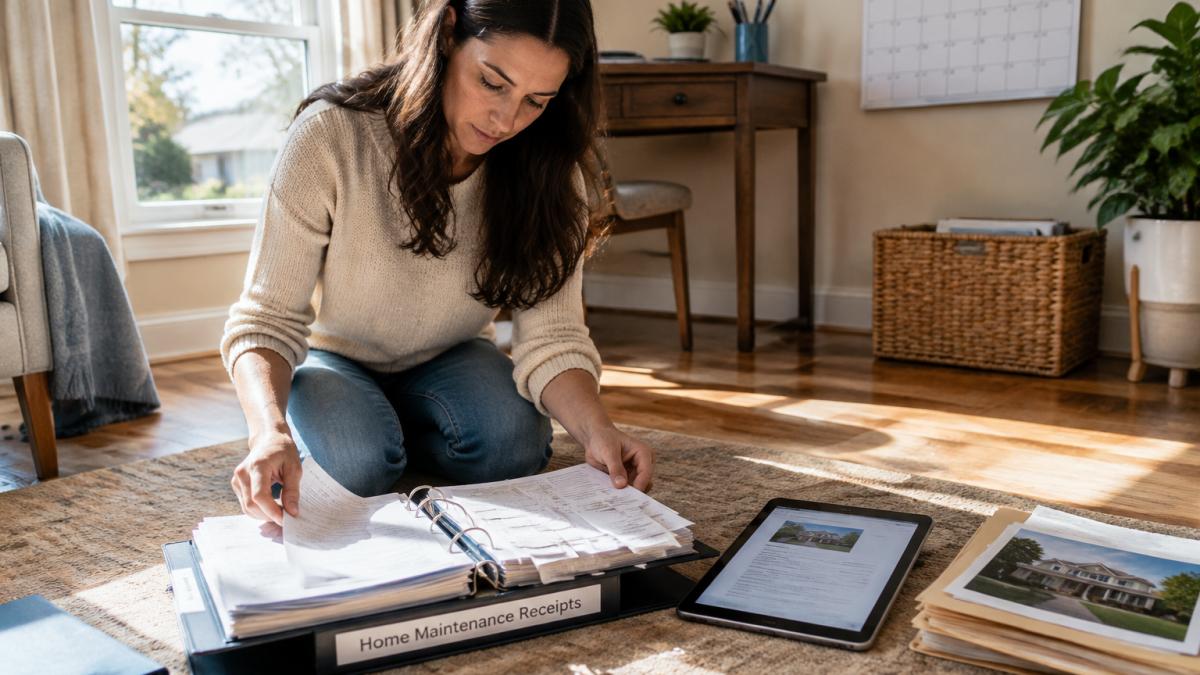
A workable system has four parts, and none of them require special software:
- A dated photo log. Photograph the same areas on a schedule: under each sink, around the water heater, the attic decking, the roof from the ground, and the caulk lines around tubs and windows. Name the files with the date so the sequence is obvious. A photo taken in March that shows dry cabinet floors is powerful evidence when a July leak is disputed.
- Receipts and invoices. Keep every repair and service visit, including routine tune-ups. A receipt for a roof inspection or an HVAC service call establishes that the system was being watched, not ignored.
- Inspection and service reports. Roofers, plumbers, and HVAC technicians often leave a written report or a digital summary. Save those. They carry a professional's assessment of condition and any recommendations, which is exactly the kind of third-party evidence an adjuster weighs.
- A simple log. Record the date, the vendor, what was done, and what was recommended. A one-page log per year is enough. The goal is a timeline, not a scrapbook.
Watch out: a folder of undated photos and loose receipts is weak evidence because it cannot establish sequence. The value comes from dates and repetition, so label files and keep the log current rather than reconstructing it after a loss.
This is also where policy and jurisdiction matter. Coverage and claim handling depend on your policy wording and the rules that apply where you live, so the same maintenance record may be weighed differently from one insurer to the next.
Wondering if the effort pays off? Our article on whether proactive home maintenance records are worth it makes the case with real claim scenarios.
Mistake 4: Confusing Sudden Damage With Gradual Deterioration
A denied claim often comes down to one question: did this happen suddenly, or did it wear out? Homeowners and adjusters answer that question very differently, and the gap between those answers is where claims die.
Consider a ceiling stain after heavy rain. The homeowner sees a storm event. The adjuster sees a roof that was already failing.
The practical problem is that "sudden" and "gradual" are not defined by how the damage felt to you.
A useful way to think about it is to separate the trigger from the condition. The trigger is the event: a storm, a freeze, a pressure spike, an appliance failure.
Here is how that plays out in realistic timelines:
| Scenario | Trigger | Condition before loss | How insurers typically see it |
|---|---|---|---|
| Supply line bursts overnight | Sudden pressure or failure | Line was sound, no prior staining | Sudden loss, usually covered |
| Cabinet floor stained and soft over months | Slow drip | Corrosion and mold present | Gradual seepage, often denied |
| Hail dents roof shingles | Named peril | Shingles were intact | Covered peril, subject to deductible |
| Roof leaks after a storm | Wind or rain | Shingles were worn and flashing loose | Wear and tear, often denied |
| Dishwasher hose fails and floods kitchen | Sudden failure | Hose was intact, no prior leak | Sudden loss, usually covered |
| Shower pan leaks into ceiling below | Slow failure | Grout and caulk had been failing | Neglect, often denied |
Watch out: the most common mistake is assuming a storm automatically converts old damage into a covered loss.
To protect yourself, document the condition of the home before the loss, not just after. Keep dated photos of the roof, the water heater pan, the area under sinks, and the caulk lines around tubs and windows.
For clarity on where the line sits, read our breakdown of whether homeowners insurance covers preventative maintenance. It explains what insurance covers versus what counts as neglect you must fund yourself.
Mistake 5: Delaying Claim Reporting After a Loss
Most policies require prompt notice of a loss. Wait too long and the insurer can deny the claim, even if the damage was covered.
Why the delay hurts you:
- Water spreads and mold sets in, making the cause harder to prove.
- The insurer may argue the damage worsened because you didn't act.
- Evidence disappears as things dry out or get thrown away.
Report the loss as soon as you find it. Then protect the home from further damage. Keep receipts for tarps, fans, or emergency repairs, because most policies cover reasonable steps to prevent more damage. Don't make permanent repairs before the adjuster sees the damage. That can void the claim.
Mistake 6: Overlooking Common Homeowners Insurance Claim Denial Reasons
Most claim denials trace back to a short list of causes. Knowing them helps you spot your own risk before a loss happens.
The National Association of Insurance Commissioners consumer guide to homeowners insurance points to the same recurring issues:
- Policy exclusions - floods, earthquakes, and neglect are typically excluded. Flood coverage needs a separate policy.
- Lack of maintenance - worn roofs, old plumbing, and rotted wood read as neglect.
- Incomplete documentation - no photos, no receipts, no proof of loss.
- Incorrect information - wrong details on the application can void coverage.
- Pre-existing damage - problems that existed before the policy started.
Read your policy language once a year. It's boring, but it tells you exactly what your insurer will and won't pay for. If you're unsure about a specific risk, ask your agent in writing.
Mistake 7: Missing the Warning Signs of a Water Damage Insurance Claim Denial
Some denials are decided before you ever file. The warning signs show up early if you know where to look.
Watch for:
- Musty smells in a basement or crawl space
- Bubbling paint or soft drywall
- A water bill that jumps without explanation
- Stains that grow after rain
- Caulk and grout failing around tubs and windows
Any one of these means water is getting in somewhere. Left alone, it becomes the gradual damage an insurer will deny.
A professional inspection can help find the source of a problem before it becomes a claim. Lone Eagle Home Services offers membership-based proactive seasonal tune-ups, and digital service reports are provided after every visit, giving you a dated record of your home's condition.
If you'd rather hand off the checking entirely, our home maintenance team for Morris County homes handles inspections, repairs, and vendor coordination under flat-rate pricing.
The hardest part of protecting a claim isn't the repair. It's remembering to check, document, and act before small problems turn into denials. That's the gap a maintenance membership closes. Lone Eagle Home Services offers one trusted team for seasonal tune-ups and on-demand repairs, flat-rate pricing, and a digital service report after every visit. Get started with Lone Eagle Home Services and turn your maintenance history into proof your home was cared for.
Frequently Asked Questions
Can homeowners insurance deny a claim because of poor maintenance?
Yes. Most policies require homeowners to maintain the property and prevent further damage. If an insurer finds that lack of maintenance caused or worsened the loss, it can deny the claim. Common examples include unrepaired slow leaks, clogged gutters that led to water intrusion, and roofs with worn shingles. Keeping dated repair records and inspection notes helps show you met your homeowner responsibilities.
Does homeowners insurance cover damage from a slow leak?
Usually not. Standard policies cover sudden and accidental damage, not gradual damage from a leak that went unfixed over time. Insurers often treat slow leaks as maintenance issues. If you discover a slow leak, document it with photos and a written timeline, repair it promptly, and keep the receipts. That record can support a water damage insurance claim denial appeal if the insurer disputes when the damage began.
What is the difference between sudden damage and gradual damage?
Sudden damage happens from a single event, such as a burst pipe, a windstorm, or a fallen branch. Gradual damage develops over weeks or months, such as a slow leak under a sink, worn roof shingles, or corrosion in a water heater. Policies typically cover sudden losses and exclude gradual wear and tear. Dated photos, maintenance logs, and repair records help you prove the damage was sudden.
What should I do after a homeowners insurance claim denial?
Read the denial letter carefully and note the specific policy language cited. Gather supporting evidence, including dated photographs, repair records, and inspection reports. File an appeal within the deadline stated in the letter, and consider a professional inspection to document the cause. If the denial stands, ask about your state's complaint process. Acting quickly preserves your options.